

The Best App for Shorting Stocks in 2026: Brokers Compared Honestly
How Interactive Brokers, TradeZero, Robinhood, Webull, Fidelity, and Schwab handle borrows, locates, and margin, plus the borrow-fee math for shorting stocks.
Interactive Brokers pairs a large lending inventory with on-screen borrow rates, TradeZero is built around locates for hard-to-borrow small caps, and Robinhood, Webull, Fidelity, and Schwab all short easy-to-borrow stocks from a $2,000 margin account with different fine print. The broker decides whether you can borrow the shares and what it costs; the chart decides whether the short is worth taking.
The best app for shorting stocks depends on what you short. Interactive Brokers is the strongest all-round pick, with one of the largest lending inventories among retail brokers and live borrow rates on screen. TradeZero is the specialist for hard-to-borrow small caps, because its locate tool finds shares the big brokers will not lend. Robinhood, Webull, Fidelity, and Schwab all let you short liquid, easy-to-borrow stocks from a margin account with $2,000 in it, and each one has a catch worth knowing before you open the first position.
Two things decide whether shorting stocks works in a given app: whether the broker can borrow the shares for you, and what it charges you to keep them borrowed. Order buttons are the easy part. This comparison covers both, with the borrow-fee and margin math worked through in dollars, then the chart side: which setups justify a short and where the buy stop goes.
Quick comparison
| App | Best for | How you find borrowable shares | Minimum to short | The catch |
|---|---|---|---|---|
| Interactive Brokers | Large borrow inventory, fee transparency | Shortable column and borrow rates in TWS | Margin account (Reg T) | Professional interface, fees shift intraday |
| TradeZero | Hard-to-borrow small caps | Built-in locator with per-share quotes | Margin account | Locate fees add up fast, most locates are same-day only |
| Robinhood | Simple shorts on liquid stocks | Shortable flag and borrow rate on the stock page | $2,000 portfolio value | Opening shorts are Good for Day only, rolling release |
| Webull | Free charts plus basic shorting | Blue downward arrow on the stock page | $2,000 margin equity | $5 per share minimum maintenance |
| Fidelity | Long-term investors adding an occasional short | Fidelity confirms availability before the order | $2,000 margin equity | 35% base maintenance on shorts |
| Schwab / thinkorswim | Shorting with a full charting platform | Borrow cost shown before you submit | $2,000 margin account | Stocks at $5 or less usually cannot be shorted |
Every app on this list needs a margin account to short. A cash account cannot sell borrowed shares at any of them.
What a shorting app actually has to do
A short sale is a sale of shares you do not own. Your broker borrows them from someone who does (another customer, its own inventory, or a lending desk), you sell them at today's price, and later you buy them back and return them. If the price fell, you keep the difference. If it rose, you pay it. FINRA's investor guide puts the risk plainly: "you must still re-buy the shares and return them to your firm," and if you re-buy at the same price or higher, after costs and interest, you lose money.
That chain gives a shorting app four jobs beyond the order ticket. It has to find shares to borrow before you sell, which regulators call a locate. It has to tell you what the borrow costs, because the fee runs every day you hold. It has to hold enough margin against the position as the price moves. And it has to tell you when the lender wants the shares back, because a recalled borrow can be closed for you at a bad price.
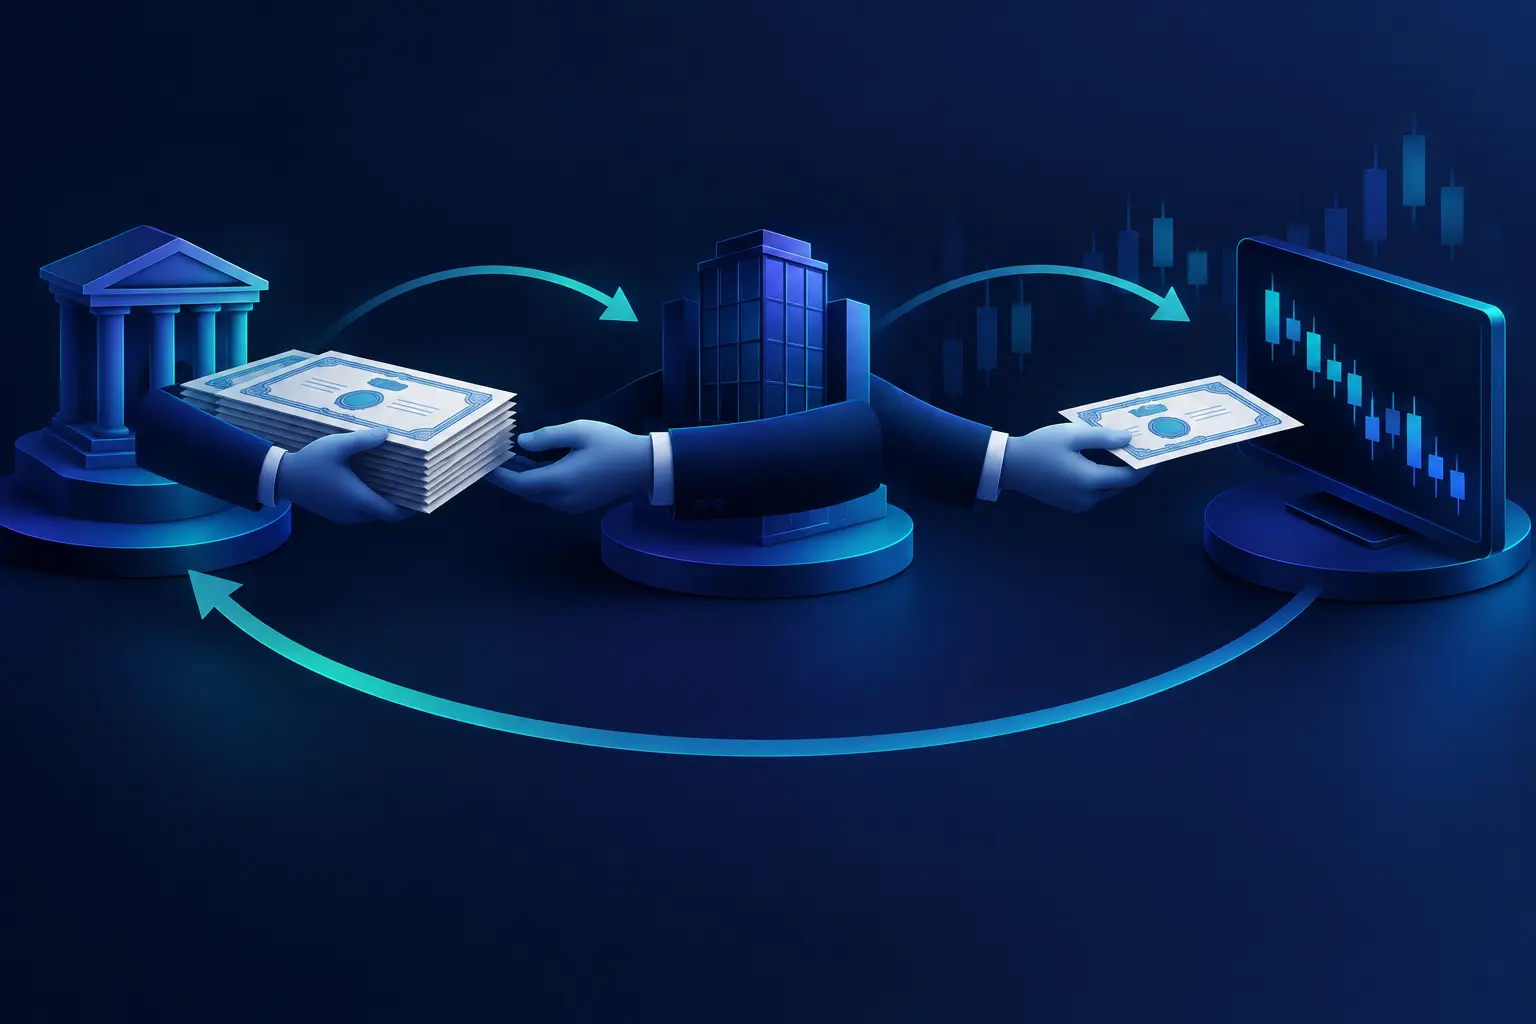
The brokers differ most on the first two jobs. A liquid large cap is easy to borrow everywhere, and the cost is usually small. The stocks that move 30% in a morning, the ones day traders most want to short, are where inventory dries up and fees climb into the hundreds of percent a year. An app that only covers easy borrows will show you "not shortable" exactly when you want it.
Interactive Brokers: best overall for shorting
Interactive Brokers is the default answer for active short sellers because it lends from one of the largest share pools a retail trader can reach and shows you the numbers before you commit. In Trader Workstation, the Shortable column displays how many shares are available to borrow and the indicative borrow rate, and the stock loan rates window shows how that rate has moved during the day and over the past month. You can check whether a borrow is cheap and stable or expensive and climbing before you sell a single share.
The fee is an annualized rate applied to the position's value, divided by 360 for each day. Two details matter. The rate on screen is indicative, so the rate you actually pay can differ when the borrow settles. And because the collateral is marked to the market every day, a short that moves against you costs more in dollars even if the rate stays flat. IBKR also offers pre-borrowing for some account types, which locks in shares before you sell, at an extra per-borrow fee.
The weakness is the interface. TWS is dense and built for professionals, and the mobile app hides much of the borrow detail. If you short a few liquid names a month, the transparency may be more than you need. If you short often, or you short mid caps where the fee can change between morning and afternoon, it is the platform the rest are measured against.
TradeZero: best for hard-to-borrow small caps
TradeZero exists for the trader who wants to short a small cap that just ran 80%. Those stocks are usually hard to borrow, and most retail brokers simply mark them unavailable. TradeZero's answer is a locator built into the platform: you request shares, see the per-share price before you confirm, and pay only if you accept.
Its locate page lists three kinds of locate. Regular locates cover hard-to-borrow stocks that are not on the Reg SHO threshold list and can be reused during the day. Single-use locates cover threshold securities, are consumed by the first short you open against them, and are typically cheaper than pre-borrows. Pre-borrows also cover threshold securities and are the only type you can hold overnight or across several days. Locate inventory opens at 4:00 AM ET and runs to 8:00 PM ET, and TradeZero supports shorting stocks priced at $0.25 and above. If you do not use a locate, you can mark it for sell-back and may recoup part of the fee, depending on demand at that moment.
The catch is cost structure. A locate is paid up front, per share, before you know whether the trade works. On a hot small cap, the locate fee alone can be a meaningful share of the profit you are aiming for, and because regular and single-use locates are intraday only, holding the short past the close means paying again for a pre-borrow. TradeZero rewards traders who short often and size carefully. It punishes anyone who buys locates on impulse.
Robinhood: simplest for liquid stocks
Robinhood added short selling for US customers on a rolling release, so some accounts saw it before others. Its short selling help page sets out the rules. You need margin investing enabled and a minimum portfolio value of $2,000. Market, limit, and stop orders are supported, but only Good for Day orders can open a short. Shorts can be opened during regular and extended hours, though not in the overnight session of the 24 Hour Market.
The borrow fee is calculated from the largest short position you held open that day, times the end-of-day price, times the quoted borrow rate, divided by 360. It accrues from the trade date until the closing trade settles and is charged monthly, on the fourth business day of the following month. Robinhood also says the cash from a short sale is not added to your buying power, so the proceeds sit as collateral and cannot fund other trades.
The fine print that matters most: Robinhood can close a short position at any time without notice, including when shares are no longer available to borrow and it is forced to buy in. It can also change borrow fees and maintenance requirements without prior notice. For a short in a large, liquid stock, that rarely bites. For a crowded short, it is the main risk of using a broker built for simplicity.
Webull: capable, with a $5 maintenance floor
Webull's short selling FAQ requires a margin account with at least $2,000 in margin equity, excluding options and pending deposits. A stock you can short shows a blue downward arrow on its detail page; if the arrow is missing, it cannot be sold short. Borrow fees and interest apply, and hard-to-borrow stocks are covered in a separate article.
The detail traders miss is the maintenance floor. Webull sets short maintenance as a percentage of market value but applies a minimum of $5 per share when the percentage comes out lower. Its own example: on an $11 stock, 30% is $3.30, so the $5 minimum applies instead. Short 200 shares of an $11 stock and Webull wants $1,000 of maintenance equity, where a flat 30% would ask for $660. On cheap stocks that floor ties up far more capital than the headline percentage suggests.
Webull's charts are good for a free app and the shortable arrow makes availability easy to check. It is a reasonable home for occasional shorts in mid and large caps.
Fidelity: conservative, and it shows
Fidelity treats shorting as a margin privilege with a high bar. Its margin FAQ says you need at least $2,000 of margin equity to sell short, that every short order depends on the stock being available to borrow, and that Fidelity must confirm that availability before the order is entered. Availability can change after you are in, which raises the chance of a buy-in.
Fidelity's numbers run above the industry minimum. The Fed's initial requirement is 50% for both long and short positions, the exchange requirement is 30% for shorts, and Fidelity's base maintenance on most securities is 35% on the short side. Hard-to-borrow positions can carry a short interest fee on top. If a stock you shorted becomes hard to borrow after you entered, you owe that fee from then on.
That makes Fidelity a sensible choice for an investor who already holds a long portfolio there and wants to short now and then, perhaps to hedge. It is a poor fit for fast intraday shorting in volatile names.
Schwab and thinkorswim: shorting with serious charts
Schwab's pitch for short sellers is thinkorswim, which is one of the most complete charting and order platforms a retail trader can get without paying. You need a margin-approved account with at least $2,000. Schwab notifies you of the current cost of borrowing before you submit a short order, and hard-to-borrow stocks carry an additional fee on top of the margin rate.
Two limits are worth knowing. Schwab's account agreement says equity securities at $5 or less usually may not be sold short, which rules out most of the small caps TradeZero traders target. And like the others, Schwab can cover a short without notice if the lender recalls the shares. For shorting liquid stocks off detailed charts, thinkorswim is excellent. For low-priced momentum names, it is the wrong tool.
The rules every app has to follow
Some limits come from the regulators, so no app can switch them off. Knowing them saves you from blaming the broker for a rule that applies everywhere.
Margin. FINRA Rule 4210 sets the minimum maintenance on short stock. For stocks at $5 or above, it is the greater of $5 per share or 30% of current market value. For stocks under $5, it is the greater of $2.50 per share or 100% of market value. Brokers can and do set higher house requirements, as Fidelity's 35% shows.
The short sale circuit breaker. Under SEC Rule 201, adopted in 2010, a stock that falls 10% or more from the prior day's close comes under a price test. The SEC's announcement says short selling is then permitted only "if the price of the security is above the current national best bid," and the restriction lasts "for the remainder of the day as well as the following day." Robinhood tells you during the order process if it applies. In practice it means you cannot hit the bid on a stock that is already down 10%; your short has to rest above it and wait to be lifted.
Locates. Before you can short, your broker needs reasonable grounds to believe it can borrow and deliver the shares by settlement. Easy-to-borrow lists make this invisible for most large caps. On threshold securities, the ones with persistent delivery failures, it is why TradeZero sells single-use locates and pre-borrows and why the mainstream apps often show "not available."
Pattern day trading. Day-trade shorts count the same as day-trade longs under your broker's day trading rules. FINRA replaced the old pattern day trader framework in 2026, but brokers have until 2027 to switch over, so what applies to you depends on your broker. Our guide to the 2026 PDT rule change covers it.
What borrowing actually costs
The borrow fee is the cost that separates a cheap short from a ruinous one, and it is easy to underestimate because it is quoted as an annual rate. Every app above uses the same basic formula: position value, times the annual rate, divided by 360, charged for each day you hold.
Take an $8,000 short: 200 shares at $40. At a 1% borrow rate, the fee is about $0.22 a day, roughly $6.67 a month. That is the typical easy-to-borrow large cap, and the fee barely matters. At 25%, which Tapeboard's daily ranking puts in its hard-to-borrow band of 10% to 50%, the same position costs $5.56 a day, about $167 a month. At 100% it is $22.22 a day.
Then there are the extremes. On Tapeboard's ranking for November 11, 2026, JZ carried the highest borrow fee in the market at 563.7% annualized, with PARA at 502.7%. An $8,000 short at 563.7% costs about $125 a day, more than $3,700 over a month. The stock has to fall 1.6% every single day just to pay the fee. Tapeboard's figures are end-of-day rates, so your broker's rate on the same stock can differ, and it can change during the session.
Bar chart of the monthly borrow cost on an $8,000 short position at five annual borrow rates: 1% costs $7 a month, 5% costs $33, 25% costs $167, 100% costs $667, and 563.7% costs $3,758. The cost rises in direct proportion to the rate, so hard-to-borrow stocks can cost hundreds or thousands of dollars a month to hold short.
Two habits keep the fee from eating the trade. Check the rate before you sell, every time, because it can jump overnight. And decide in advance how long the thesis needs. A swing short in an easy borrow can be held for weeks. A short in a stock costing 300% a year is a trade measured in hours, and the fee belongs in your target price.
Dividends add a second cost. When a stock you are short pays a dividend, you owe the lender the equivalent amount, which Robinhood's help page spells out. Announced dividends can also push borrow rates up in the days before the record date, so a short held through one can cost more than it looks.
How a short gets a margin call
Margin on a short works in the opposite direction to margin on a long: the account weakens as the price rises, and the price has no ceiling. The FINRA investor guide notes that shorting carries strict margin requirements because you are selling stock you do not own.
A worked example makes the mechanism concrete. You have $5,000 in cash and short 100 shares at $50, adding $5,000 of proceeds. The account holds a $10,000 credit balance against a $5,000 short. Your equity is the credit minus the current value of the short. At Fidelity's 35% base maintenance, equity has to stay above 35% of the short's market value.
At $50, equity is $5,000 against a requirement of $1,750. At $65, equity is $3,500 against $2,275, still fine. Past roughly $74, the lines cross: equity falls to about $2,593 while the requirement rises to the same amount, and you get a margin call. At the FINRA minimum of 30%, the call comes a little later, near $77. A stock that rallies 50% in a week, which happens to crowded shorts, would put the account in a call either way.
Line chart of a 100-share short opened at $50 with $5,000 of cash. As the share price rises from $50 to $80, account equity falls from $5,000 to $2,000 while the 35% maintenance requirement rises from $1,750 to $2,800. The lines cross between $70 and $75, at about $74, which is where the margin call comes.
Low-priced stocks are harsher. Under Rule 4210, a short in a stock below $5 needs the greater of $2.50 a share or 100% of its value. Short 1,000 shares of a $3 stock and the requirement is $3,000, the full value of the position, on top of the proceeds. Add a $5 per share floor like Webull's on stocks just above $5 and the capital tied up per share can exceed what the stock trades for.
The broker can also close a short for reasons that have nothing to do with your equity. Robinhood, Fidelity, and Schwab all reserve the right to buy in a short without notice when the borrow disappears. Size for that possibility: a forced cover at the top of a spike is the worst fill a short seller can get.
Squeezes, gaps, and why the loss has no ceiling
A long position can lose 100% at most. A short has no such limit, because a stock can keep rising. That is the single fact every shorting app's disclosures circle around, and it changes how you manage the trade.
A short squeeze happens when a heavily shorted stock rises and short sellers cover at the same time. Their buy orders push the price higher, which forces more covering. Crowded shorts in small floats are the classic setup, and they are also the stocks with the highest borrow fees, so the most expensive shorts to hold are also the ones most likely to squeeze.
Gaps are the other danger. Your protective order on a short is a buy stop placed above the market. If the company announces good news overnight and the stock opens 25% higher, the stop triggers at the open and fills near that price, far above your stop level. Robinhood says plainly that there is no guarantee the price will decrease. A stop limit can cap the fill price, but if the stock gaps past your limit, the order does not fill and you are still short.
Three habits reduce, without removing, the risk. Size every short from the stop distance and assume the realistic loss could be twice that on a gap. Avoid holding shorts through scheduled news like earnings unless the position is small enough to survive a large gap. And watch the borrow rate and short interest: a rate that jumps from 5% to 60% in two days is often the first sign of a crowded trade.
Where Quant AI fits
The brokers above decide whether you can borrow the shares and what it costs. None of them tell you whether the short is a good idea, and that part comes from the chart. Quant AI reads a screenshot of any stock chart and marks the trend, the support and resistance levels, and the setup it finds in seconds. For a short seller, that means a quick read on whether price is putting in lower highs, whether a support level has broken, and where the nearest resistance sits for the buy stop.
It does not place orders, find borrows, or quote fees, so you still need one of the apps above to execute the trade. It is most useful as a second opinion on a chart you are already looking at, before you pay for a locate.
The chart setups worth shorting
The most expensive shorting mistake is the "it's gone up too much" short, where the only reason for the trade is that the stock looks high. Strong stocks can stay high, and a squeeze will take your money on the way. The setups that justify a short have a broken structure and a clear level that proves the idea wrong.
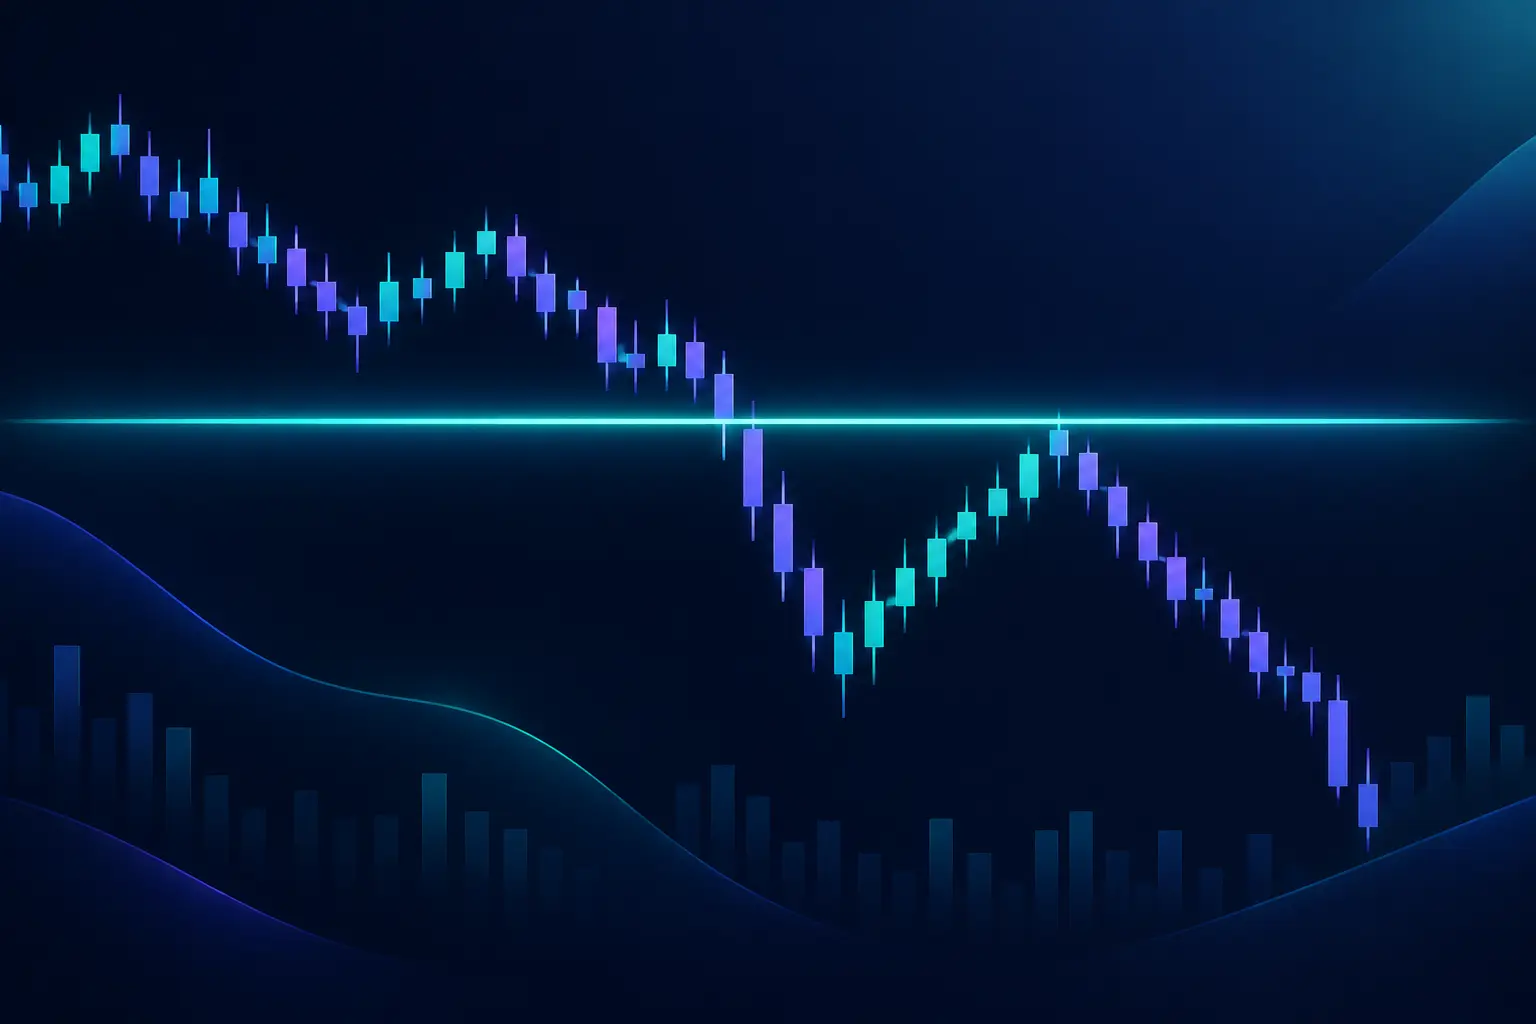
The bear flag is the most common. A sharp drop, then a shallow, orderly bounce on lighter volume, then a break of the bounce's low. Our bear flag guide covers the five checks that separate a real flag from a base. Tops like the head and shoulders and the double top give a short entry when the neckline breaks. A failed breakout, where price pushes above resistance and closes back below it, traps late buyers whose stops become fuel for the move down. All of these are covered in the stock chart patterns guide.
Here is a worked breakdown short with real numbers. A stock has held support at $40 for three weeks. It breaks to $39.20 on heavy volume, bounces back to $40.20 the next morning, and stalls there; old support is now acting as resistance. You short at $39.80 as it turns down from the retest, with a buy stop at $41.30, above the retest high and the old support zone. That is $1.50 of risk per share. With a $10,000 account risking 1%, or $100, the size is 66 shares, about $2,630 of stock. Your first target is the next support at $36.80, $3 away, for a reward-to-risk of 2 to 1.
Before entering, check the app's side of the trade. Is the stock shortable, and what is the borrow rate? At 2% a year, the fee on $2,630 is about $0.15 a day, irrelevant. At 150%, it is about $11 a day, which eats more than a tenth of your planned risk every day you hold, so the trade has to work quickly or not at all. Is Rule 201 in force? If the stock fell 10% yesterday, you can only short above the bid. And remember the gap: if news sends the stock to $44 overnight, your $100 planned loss becomes about $277.
How to choose
Pick by what you short, how often, and how long you hold.
- You short small caps that just ran: TradeZero, because the locator finds shares the mainstream apps will not lend. Budget for locate fees as a cost of every trade.
- You short often across many names: Interactive Brokers, for its inventory and the borrow rates shown in TWS before you sell.
- You short liquid stocks now and then from your phone: Robinhood or Webull. Both need $2,000; Robinhood opens shorts as day orders only, Webull's $5 floor raises the requirement on cheap stocks.
- You hedge a long portfolio: Fidelity or Schwab, where your long holdings already sit. Expect stricter margin and limited access to hard-to-borrow names.
- You want the best free charts in the same app as your shorts: thinkorswim at Schwab, as long as you are shorting stocks above $5.
Whatever you pick, open the borrow rate, the maintenance requirement, and the buy-in policy for the specific stock before you trade. Those three numbers vary more between brokers, and between days, than any commission.
Frequently asked questions
What is the best app for shorting stocks?
For most active short sellers, Interactive Brokers, because its lending inventory is large and it shows the borrow rate before you sell. For hard-to-borrow small caps, TradeZero. For occasional shorts in liquid stocks, Robinhood and Webull are simpler and work from a $2,000 margin account.
Can you short stocks on Robinhood?
Yes, for US customers with margin investing enabled and at least $2,000 in portfolio value. It rolled out gradually, so not every account got it at once. Opening shorts must be Good for Day orders, and Robinhood can close a short without notice if the borrow is no longer available.
How much money do you need to short a stock?
Robinhood, Webull, Fidelity, and Schwab all require $2,000 in a margin account. On top of that, the position needs initial margin (50% under the Fed's rule, on top of the sale proceeds) and ongoing maintenance of at least 30% for stocks at $5 and above, more at many brokers.
Can I short a stock in a cash account?
No. Every broker in this comparison requires a margin account to short, because you are selling borrowed shares. If you want bearish exposure without a margin account, buying a put option limits your loss to the premium paid, though options carry their own risks.
Why can't I short a stock?
Usually one of four reasons: your broker has no shares to lend (the stock is not shortable or is hard to borrow), the stock is under the Rule 201 price test after a 10% drop, the stock's price is below your broker's minimum (Schwab usually will not short stocks at $5 or less), or your account lacks margin approval or the $2,000 minimum.
What does hard to borrow mean?
The stock has few shares available to lend, so borrowing it costs more and the broker may require a locate first. Tapeboard's daily rankings label fees of 10% to 50% a year as hard to borrow and above 50% as extreme. Hard-to-borrow shorts can also be recalled, which forces you out.
Can you lose more than you invest when shorting?
Yes. A stock's price can keep rising without limit, so a short's loss has no ceiling, and gaps can fill your buy stop far above where you set it. That is why sizing from the stop distance and avoiding overnight news matter more on shorts than on longs.
Can I short stocks in extended hours?
It depends on the broker. Robinhood allows opening shorts in regular and extended hours but not in the overnight session. TradeZero's locates run from 4:00 AM to 8:00 PM ET. Liquidity outside regular hours is thinner, so fills can be worse.
I sold a stock I owned after it dropped. Is that shorting?
No. Selling shares you own just closes your position. Shorting means selling shares you borrowed, so you profit if the price falls after you sell and lose if it rises. Beginners confuse the two often, because both start with a sell button.
The bottom line
Interactive Brokers is the best all-round app for shorting stocks, TradeZero is the specialist for hard-to-borrow small caps, and Robinhood, Webull, Fidelity, and Schwab cover liquid stocks from a $2,000 margin account with different trade-offs. Choose the broker by the borrows you need, then read the borrow rate and the maintenance requirement on every trade.
The app handles the borrow. The chart decides whether the short deserves the risk, and on a short that risk has no ceiling. Size every position as if a gap will hit it.





